A powerful piece by former British Prime Minister John Major about what he believes to be the truth about Brexit and the problems with the political extremes (in Britain and everywhere else).
A powerful piece by former British Prime Minister John Major about what he believes to be the truth about Brexit and the problems with the political extremes (in Britain and everywhere else).
HIGHLIGHTS
MARKET RECAP
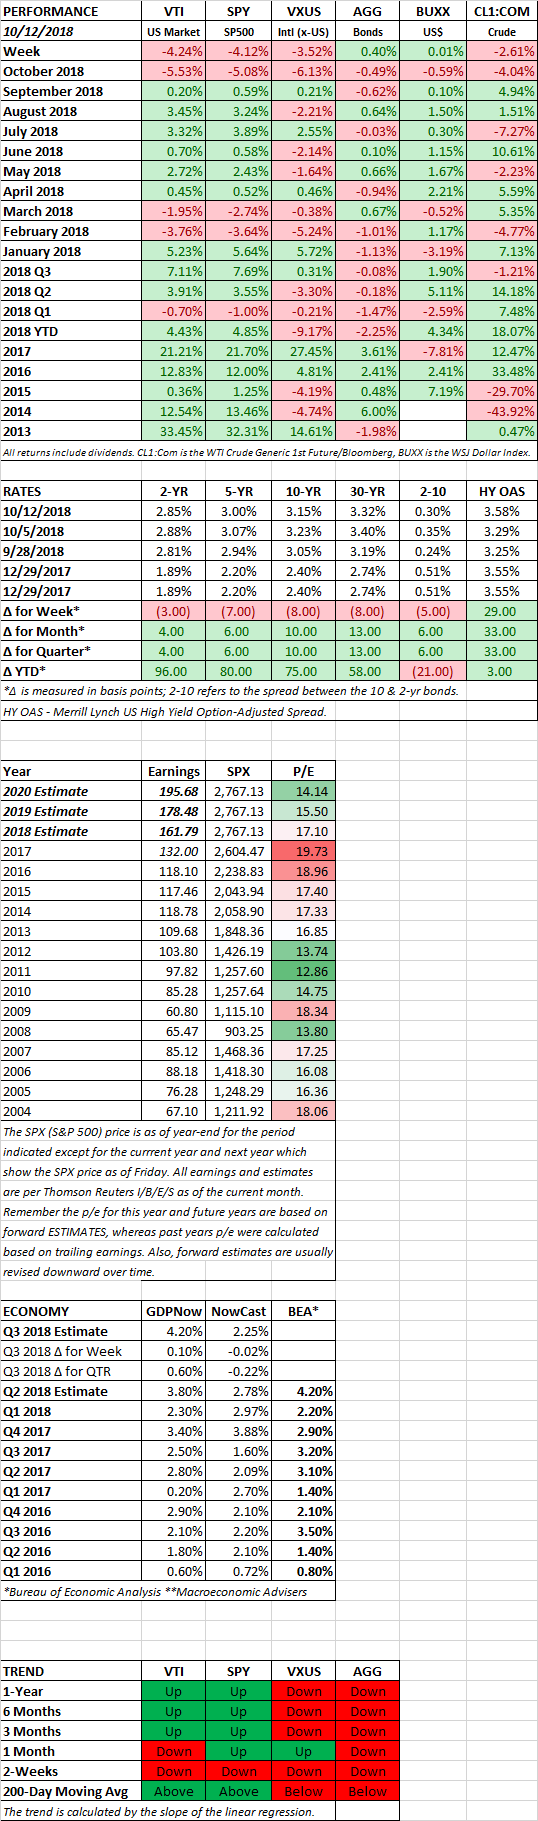
Stocks fell hard on Wednesday and Thursday, leading to a 4.24% decline in the US and 3.52% for international equities on the week. US stocks have now fallen 6% since the September 20 high. Small stocks, which hit their high on August 29, entered correction territory on Thursday, down 10.3%, before a small rally on Friday.
With the 6% drop, the S&P has now fallen by more than 5% off its peak for the second time this year. This has happened nine times in the last 12 years. So a drop of 5% or more at least two times during the year is nothing out of the ordinary. But that doesn’t matter it can’t get worse from here.
Higher interest rates took some of the blame for the drop in prices. President Trump was leading the bandwagon, saying that the Fed was “out of control” for raising interest rates. Trump also stated that “I think I know about it better than they do” in regards to monetary policy. So maybe Trump should double as Fed Chair also. We wrote back on July 22 that Trump was setting up Fed Chair “Powell to be the fall guy” in the event the economy was to slow down. But if higher interest rates were to blame, it was the long end of the curve that seemed to cause most of the concern. The Fed has more of an influence on the short end.
Trade tensions also share the blame. The US and China appear no closer to resolving their differences. Tariffs, which are set to rise further in a few months, are a tax paid for by Americans. Tariffs also mean higher prices, which means higher inflation, which means higher interest rates.
While the US economy continues to look strong, the global outlook has weakened. In a new report, the International Monetary Fund wrote that “downside risks to global growth have risen in the past six months and the potential for upside surprises has receded.” The IMF now projects global growth at 3.7% for 2018-2019, that is down from 3.9%. The IMF wrote that “In the United States, momentum is still strong as fiscal stimulus continues to increase, but the forecast for 2019 has been revised down due to recently announced trade measures.”
You can throw in earnings fears into the blame group. PPG, the maker of paints and coatings, revised their earnings outlook lower. The company said that rising costs for raw materials and oil, as well as lower demand from China, are impacting profits. The stock fell 10% on the news. Overall earnings estimates for the S&P 500 for 2018 reached their peak on September 14 at $162.25 according to Thomson Reuters, and have since fallen slightly to $161.79. 2019 estimates have also fallen, again, just slightly, by 0.23%, since September 7. But previous to September, estimates had been on a slow climb higher for several months. So the subtle change in earnings estimates might be hurting the market.
One positive signal is that as stocks have fallen, at least one valuation metric is now on the undervalued side. The forward p/e ratio for the SP500 is now at 15.7, versus a 16.1 long-term average. However, higher interest rates and further inflation could push future earnings estimates down.
SCOREBOARD
HIGHLIGHTS
MARKET RECAP
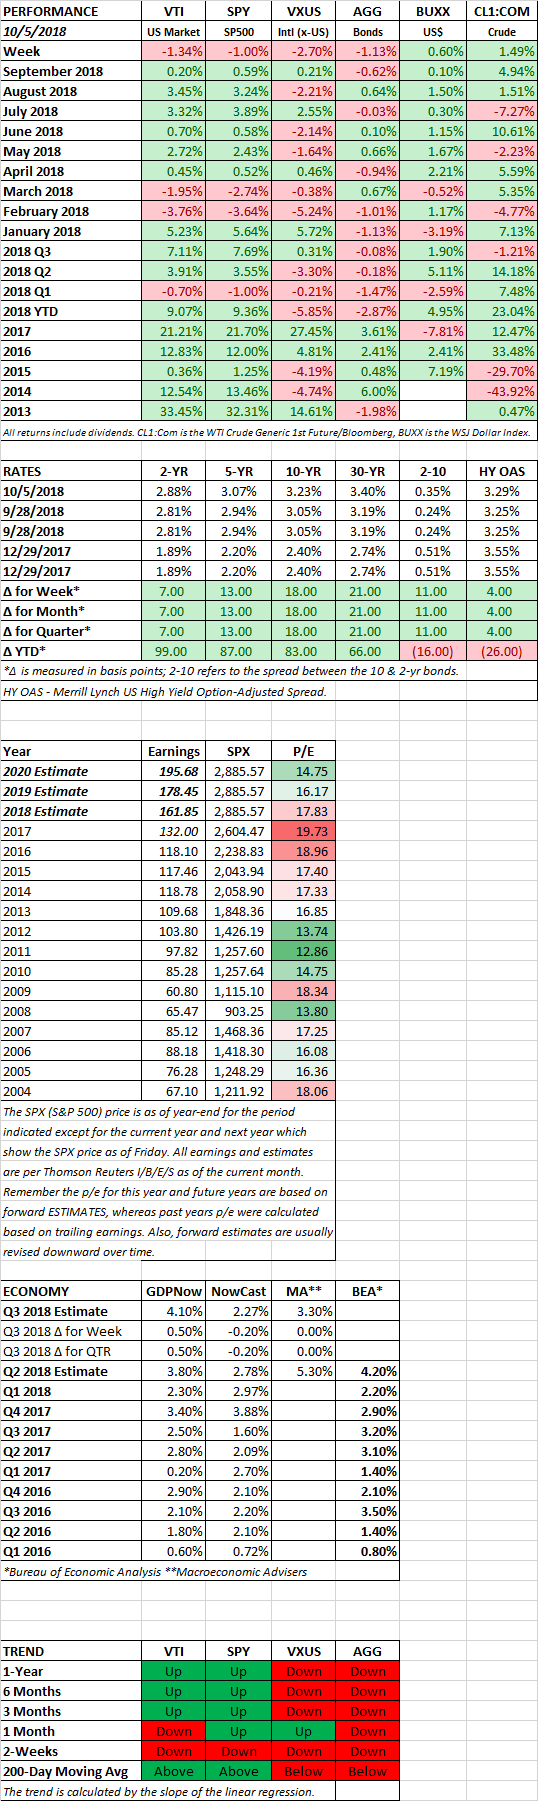
Markets were down across the world this week. US stocks dropped by 1.34% and international stocks fell by 2.70%. There were two big stories this week. First, the US and Canada agreed to a new trade deal, taking a trade war off the table between the two countries, although the agreement must still be ratified by the respective legislatures. The second big story was the pop in interest rates at the end of the week. That led to a decent size sell-off on Thursday and Friday. Other factors that hurt the market was the rise in Italian bond yields due to a rising deficit that is not in line with the European Union. Oil prices continued their upward rise, climbing another 1.5% on the week. Brent crude is now at $86 per barrel which is a 2018 high. And it was reported by Bloomberg that China planted chips on computer motherboards to spy on US companies, raising tension between the US and China another notch.
INTEREST RATES
Bond yields spiked this week. The 10-year jumped by 18 basis points to close at 3.23% and broke out to a new high. Matching levels that were last seen in 2018. Strong economic data, and an unemployment rate that dropped to the lowest level since 1969 point to continued rate hikes down the line, more than the market had been anticipating.

US/CANADA
The US and Canada agreed on a new trade pact to replace NAFTA. The next step would be getting it approved by Congress and the Canadian legislature, probably early in 2019. On the surface, the agreement appears to be pretty much the same as NAFTA, with some minor changes. But one thing for sure, the agreement is much better than no agreement at all.
Multinational companies will be able to keep together their intricate mix of supply chains between the US, Canada, and Mexico. The agreement also opens up new markets for US dairy farmers. Duty-free cars will now have to have 75% of their content produced in North America and 40% manufactured by labor being paid at least $16 per hour.
There will continue to be an independent dispute-resolution system. With this pact out of the way, Trump can now concentrate on China.
LABOR MARKET
Nonfarm payrolls were up by 134,000 in September, which was less than the consensus estimate of 180,000. It was the smallest gain in one year but was probably impacted by Hurricane Florence. Also, the prior two months were revised up by 87,000. The unemployment rate dropped to 3.7% from 3.9%, the lowest rate since December 1969. Average hourly earnings were up by 2.8%. The job market remains extremely tight.
SCOREBOARD
HIGHLIGHTS
MARKET RECAP
US stocks were down by about 1/2% and international stocks fell by 0.83%. Bonds were up 0.06%. Crude continued to spike higher, up 3.49% for the week and almost 5% for the month. Oil prices are expected to continue to rise as sanctions on Iranian oil begin to start in November.
The Fed, as expected, raised interest rates by 1/4%. It was the eight increase since 2015. A trade deal was signed with South Korea and a final deal with Canada is supposedly close. But trade problems with China persist and that will feed into higher prices here in the US as supply chains are interrupted and become less efficient.
TESLA
Tesla agreed to a $40 million dollar settlement with the SEC to settle fraud charges from Elon Musk’s tweet that he had an offer to take the company private. Tesla will have to bring in an independent chairman to replace Musk and add two independent directors and put controls on Musk’s communications.
SOUTH KOREA
Trump signed a free-trade agreement with South Korea. It was the first signed agreement by Trump that will help to open markets rather than close them.
EQUITIES SURPASS REAL ESTATE
Here is a statistic that points to those that argues that equities are way overvalued. In Q2, the value of equities jumped over real estate for the biggest share of household wealth according to Steve Blitz of TS Lombard. The last time that happened was during the dot-com era.
SENATE JUDICIARY PANEL
It was painful to watch, but Supreme Court nominee Brett Kavanaugh and Dr. Christine Ford faced off in Senate testimony on Ford’s accusations that Kavanaugh attempted to rape her in high school. The episode had little impact on the markets but was a prime example of the divide in this country between the two parties.
SCOREBOARD

Let’s start keeping track:
HIGHLIGHTS
MARKET RECAP
US stocks advanced by 0.59% despite the trade war being ramped up another notch. International stocks jumped, +2.63%, helped by a falling dollar, which declined by 0.55%. Interest rates were up across the board, and the spread between the 10 and 2-year treasury increased by 5 basis points to 26. The 10-year note broke through the 3% barrier and is yielding 3.07%.
TRADE WAR
Trump upped the ante in the trade war battle by implementing the tariffs on $200 billion of Chinese products that he had previously threatened. The tariffs start at 10% and then go up to 25% by year-end. China responded with $60 billion. Trump then said he would hit back with another $267 billion. When economists talk about how trade wars start and turn from something small into something big, this is the playbook. And Trump and his Chinese counterpart are playing their parts perfectly. Should Trump go all the way with the tariffs as described, Oxford Economics is forecasting a 1% hit to GDP. Expected growth next year per the Federal Reserve is about 2.4% (before the trade war).
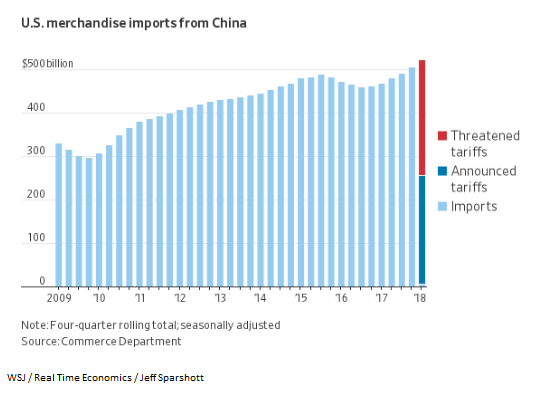
The US is right in that China does not trade fair regarding technology transfer and intellectual property. Trump’s obsession with China’s trade surplus is wrong. The administration also has not laid out exactly what they want, leading some to believe that Trump really does not want a deal, and the tariffs are more about hurting China than trying to build a better economy.
Chinese company Alibaba said they would not add a million US jobs they had promised at an earlier point.
Trump’s hardline approach may or may not ultimately work, but in the meantime, as the tariffs eventually work their way through the economy, businesses and employees will suffer, inflation will increase, and growth will either slow or decline.
CORPORATE DEBT
Randall Forsyth writes in his weekly “Up & Down Wall Street” column in Barron’s that Stephanie Pomboy of MacroMavens has been warning about corporate debt. Corporate interest expense is at a record, even while interest rates are still relatively low. But given the excessive debt burden, companies will be cutting back borrowing by 14.6%, compared to the prior year, an indication that slowly increasing interest rates are causing pain. Pomboy argues that equities have been rising with global central bank stimulus for years now, and when that ends early next year, interest rates will rise further, cutting into corporate profits, and the fuel that has driven this long rally will be spent.
SCOREBOARD
HIGHLIGHTS
MARKET RECAP
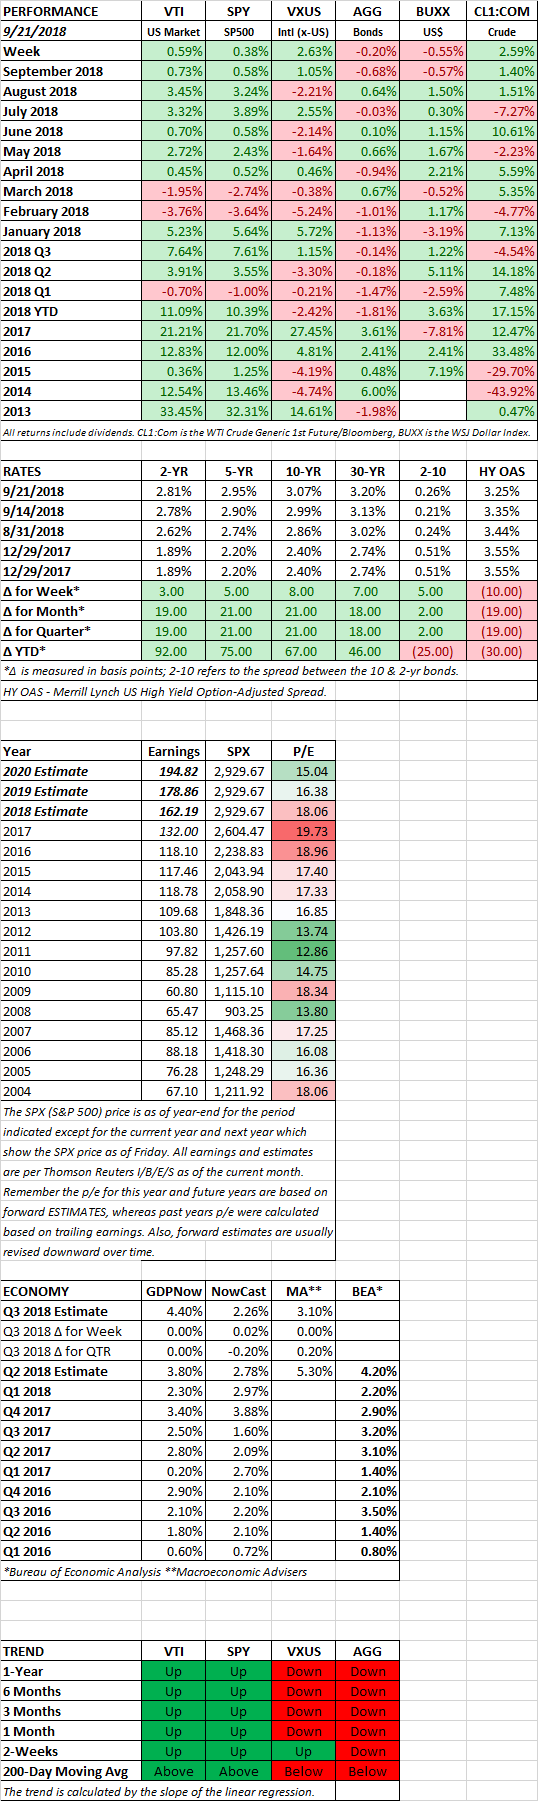
US stocks ended up 1.14% on good economic reports. Equities were also helped by emerging markets, which were up by 0.70%, calming fears, at least for now, of a never-ending fall that would drag down US stocks. International stocks increased by 1.52%. Technology had a good week, up 1.8%. Apple released its new line up of products and shares increased by 1.1%.
ECONOMY
It was a week of strong economic reports. Industrial production was up 0.4% in August and July was revised up to 0.4% from 0.1%. Year over year, industrial production is up by 4.9%, the highest number since December of 2010.
Retail sales were up by 0.1% in August, showing some recent moderation in growth. But year over year, sales are up by 6.5%, the most since December of 2011.
The University of Michigan Consumer Sentiment Index reported its second-highest reading since January of 2004, at 100.8.
DEFICIT
Barron’s cover story this week was on U.S. debt. We have written and spoken about this many times in the past. The deficit is one of those things that is not a problem until it becomes a problem. And when that happens, it is not going to be pretty. At some future point, investors are not going to want to finance U.S. debt. And then interest rates will skyrocket, or the Fed will have to print dollars, and the dollar will depreciate.
America currently owes $15.7 trillion, which is 78% of the gross domestic product (GDP). The Congressional Budget Office (CBO) estimates that in a decade debt will be $28.7 trillion, or 96% of GDP. And that assumes no catch up in infrastructure, no financial crisis, and no wars. It is one thing if debt increases in line with GDP growth. But that is not the projection. The CBO estimates nominal GDP growth at 4% and debt to rise at 4.9% over the next 10-years.
Neither political party has any interest in addressing this serious issue.
BUYBACKS
For the first half of the year, stock buybacks made up the largest percentage of cash spending by companies in the S&P 500. Buybacks were up by 48% and totaled $384 billion during that period. Capital spending increased by 19% to $341 billion.
TARIFFS / TRADE WAR
For all the talk of tariffs and a trade war, so far to date, they have yet to be implemented in mass. Currently, tariffs on imports effect about $113 billion in goods. That is 4% of all US exports. About $70 billion has been implemented on US exports or about 3% of the total. Trump has threatened tariffs on another $700 billion of imports.
SCOREBOARD
HIGHLIGHTS
MARKET RECAP
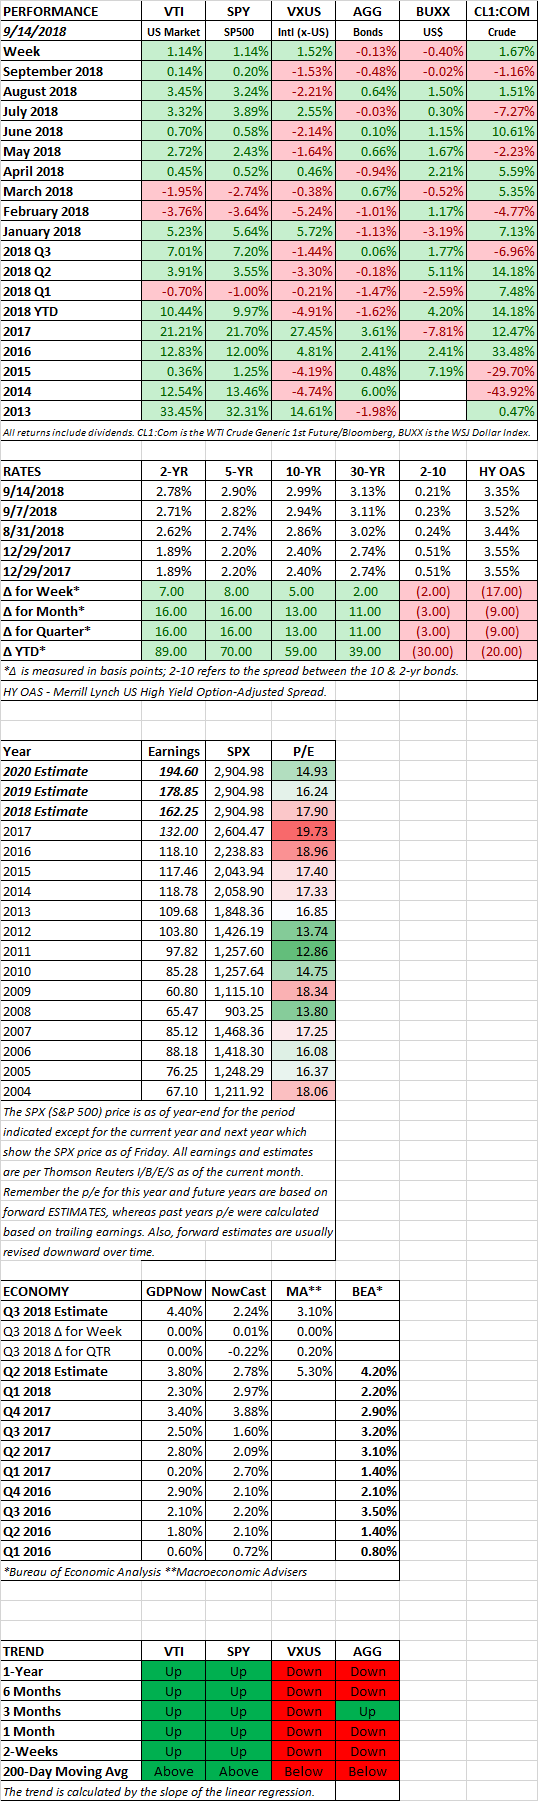
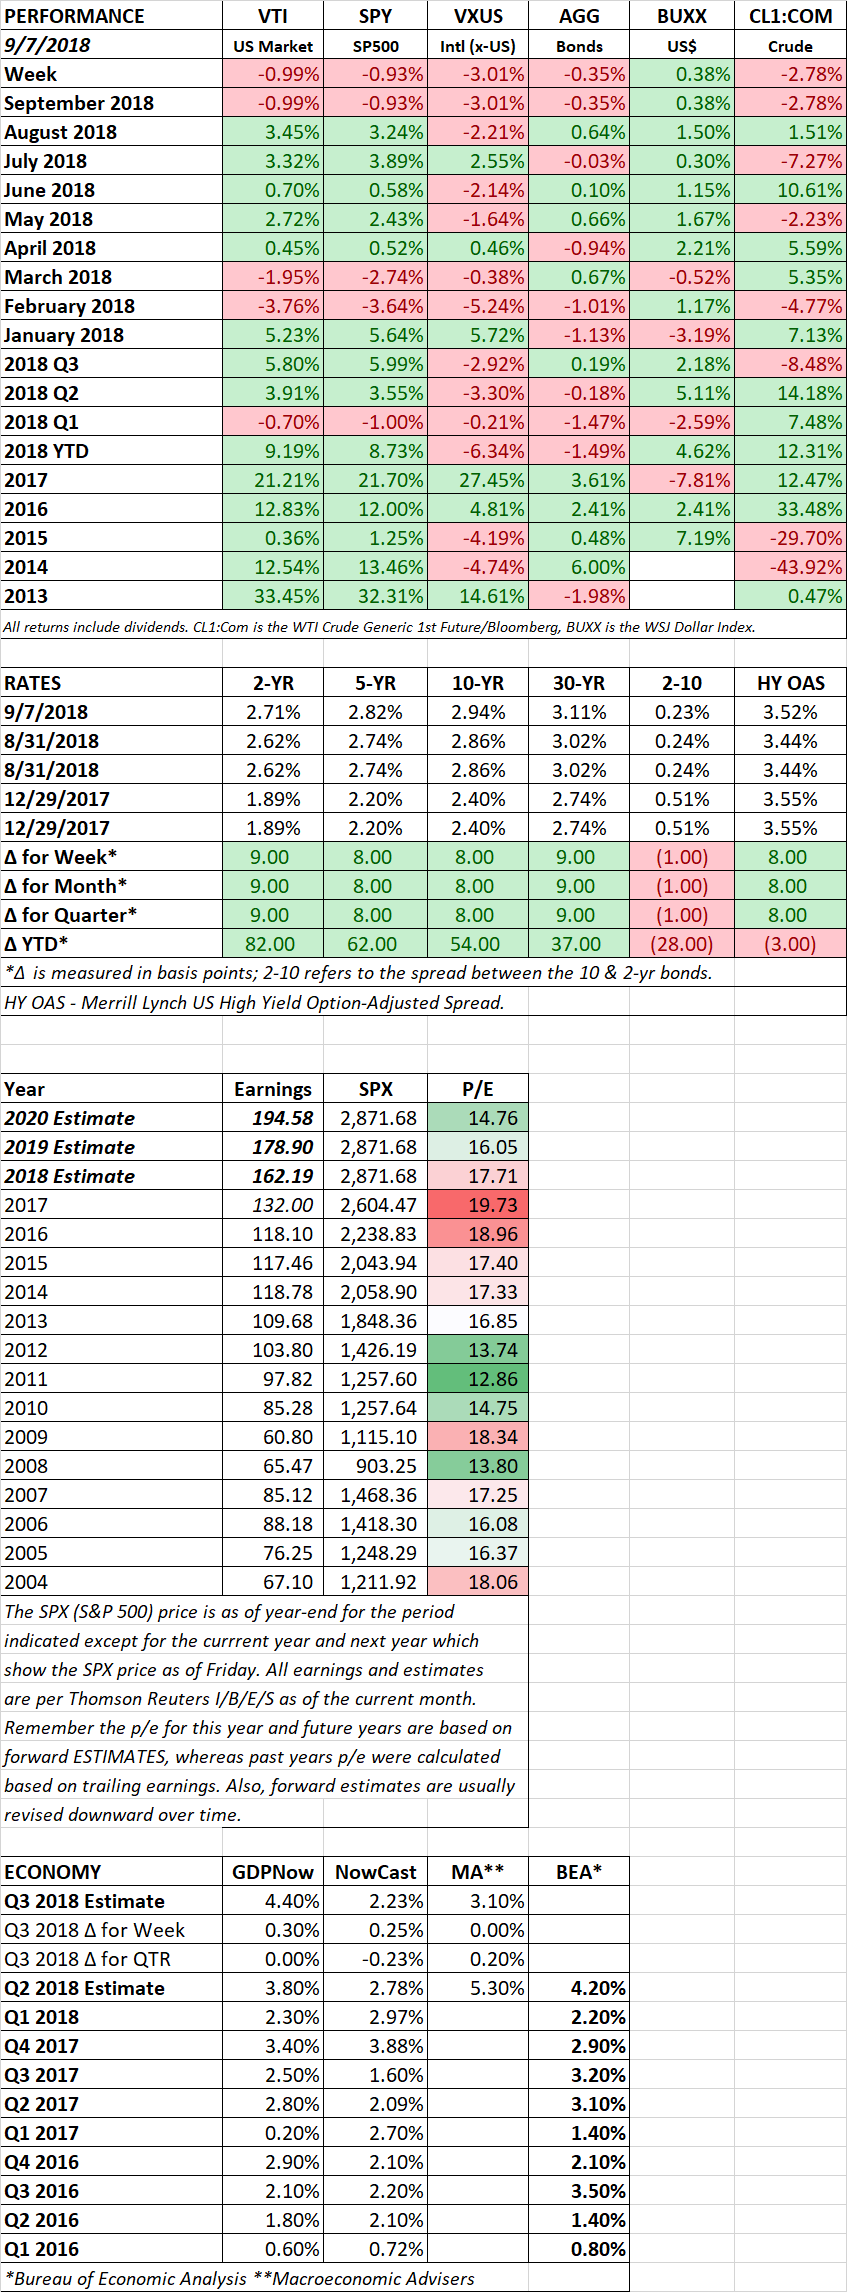
Markets around the world fell. US stocks were down by 1% and international stocks fell by 3%. Emerging markets equities entered a bear market (see below) and there is fear of contagion. Bonds fell by 0.35% on a rise in interest rates. The US economy continues to show strength.
The NASDAQ, composed primarily of technology stocks, dropped 2.6%, its worst performance since March. Social media stocks were under the spotlight as they returned to testify in front of Congress about foreign influence on elections. The Department of Justice said it would look into the “stifling” of voices on social media. Semiconductor stocks dropped on lower earnings expectations. Stocks were hurt further on Friday when Trump said that an additional $267 billion in tariffs on China, on top of what was previously announced, is now on the table. Tesla dropped by 6% to $263 when Elon Musk was shown smoking marijuana in an interview.
ECONOMY
Nonfarm payrolls increased by 201,000 in August and private-sector wages increased by 2.9% year over year. The unemployment rate remained unchanged at 3.9%. The 2.9% increase in the wage rate was the highest of this expansion. While that is good for workers, it could cut into corporate profit margins and give the Fed more leeway to increase interest rates.
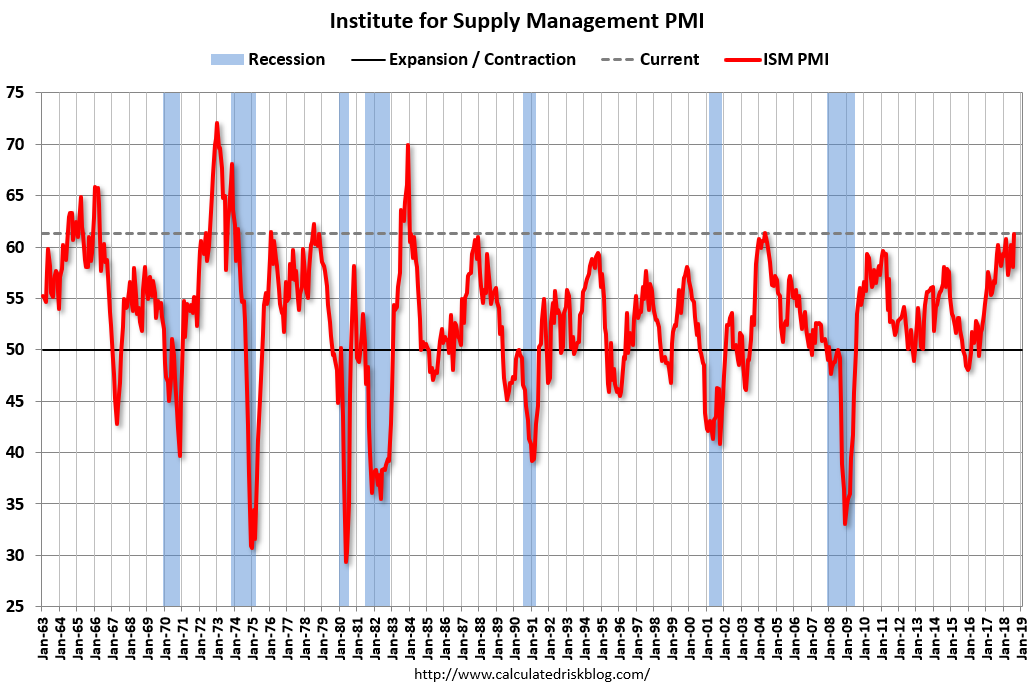
The ISM Manufacturing Index jumped higher in August to 61.3, up from 58.1. That is the highest level since May of 2004 and indicates strong growth ahead. However, according to the ISM report, “Respondents are again overwhelmingly concerned about tariff-related activity, including how reciprocal tariffs will impact company revenue and current manufacturing locations.”
The Global Manufacturing PMI fell by 0.3 points in August to 52.5. It was the seventh drop in eight months. But the index still remains in expansionary mode (greater than 50) for the 30th consecutive month. Developed markets, led by Europe turned in better numbers than the emerging markets.
The Philly Fed State Leading Indexes project growth in 49 states over the next six months, however, growth rates are expected to moderate.
BEAR MARKET INDICATOR
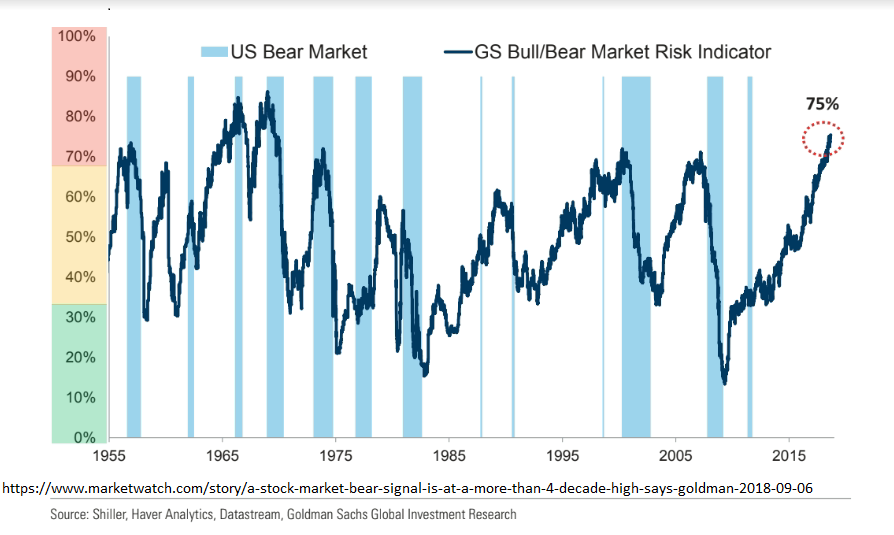
The Goldman-Sachs Bull-Bear Indicator, which relies on five market factors, is flashing its strongest warning signal since the 1970s. High stock market valuations and a tight labor market are two of these key factors. However, Goldman is not anticipating a deep bear market, but they are forecasting lower returns ahead. Moderating factors include a low-interest rate environment, subdued inflation, and an accommodative monetary policy around the world.
EMERGING MARKETS
Emerging markets dipped into bear market territory on Thursday. The MSCI Emerging Markets index is now off just more than 20%. A fall of 20% or more is considered a bear market. A rising dollar, trade tensions, and falling commodity prices shoulder most of the blame. The rising dollar makes it more difficult for countries with debt denominated in the US currency to repay their loans. Rising trade tensions could put a damper on global trade that some emerging market countries count on, as well as lead to an economic slowdown. Raw-material prices are down about 10% since the May peak. Emerging market countries like Brazil, Chile, and Indonesia are major commodity exporters.
MORE DRAMA IN DC
Bob Woodward’s new book, “Fear”, was published and paints a portrait of a dysfunctional White House. And the NY Time published an op-ed by an anonymous author who is supposedly a senior official in the White House. The piece says that there is a group operating to control the worst instincts of Trump and to basically act as the adults in the room.
SCOREBOARD
MARKET RECAP
Stocks were up for the week but down on Friday on worries that Trump was planning to go forward with more tariffs on Chinese imports and on reports that the US and Canada were not able to reach a trade deal as hoped for.
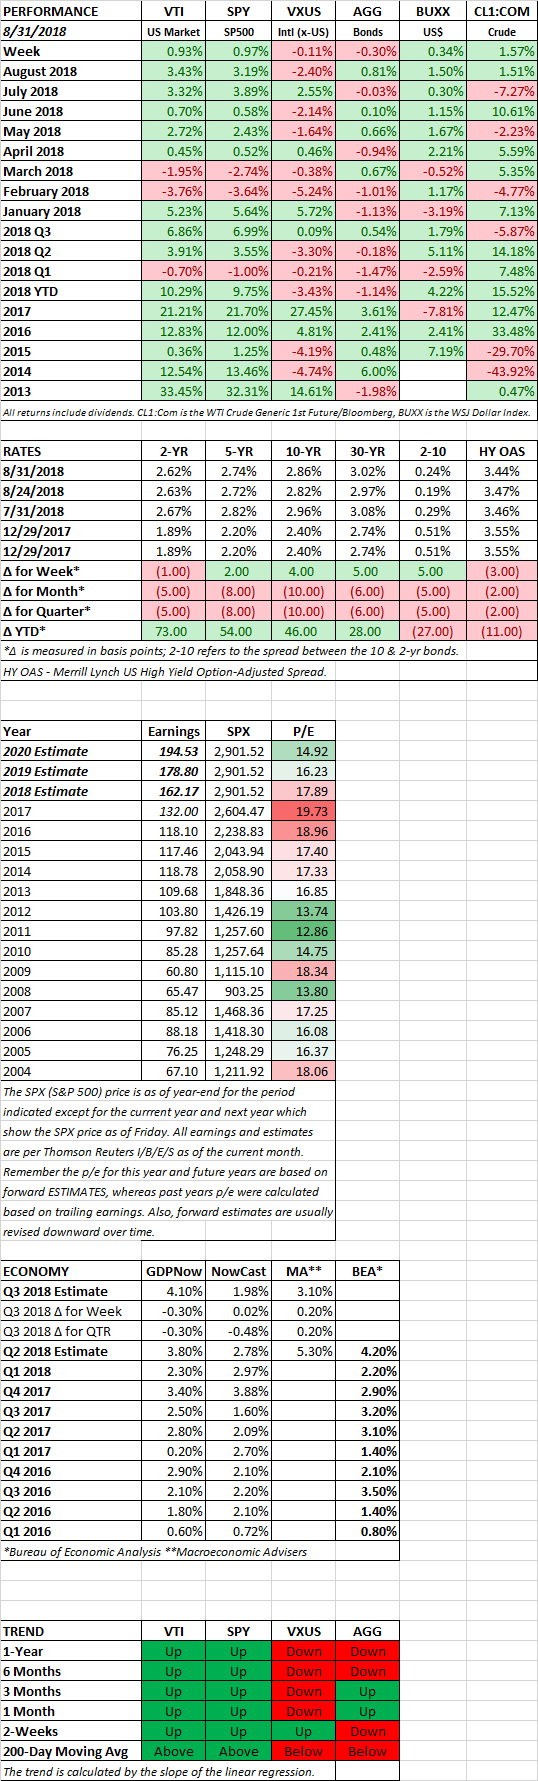
For the week, US stocks were up 0.93% and international stocks fell by 0.11%. Bonds dropped by 0.30%. August was another good month for US stocks, +3.43%, while international stocks fell by 2.4%. Bonds were up 0.81% for the month. The NASDAQ had its best August performance in 18 years, +5.7%, powered by Apple (+20%), Amazon (+13%) and Netflix (+9%).
A strong economy coupled with strong profits has been the main driver behind this market. The GDPNow model from the Atlanta Fed is projecting Q3 growth at 4.1%, Macroeconomic Advisors is at 3.1% and the NY Fed’s Nowcast is at 1.98%. Meanwhile, corporate profit projections continue to improve for 2018, 2019 and 2020. They are up by 0.67%, 1.29% and 0.69% from 13 weeks ago (one-quarter of the year). However, the rate of change has been falling in recent weeks.
US / MEXICO
The US and Mexico came to terms on an updated NAFTA agreement. The agreement would lessen dispute resolution measures and would require higher paying jobs in auto-factories. The focus then turned to wrap up a deal with Canada by Friday but that did not happen.
VIX and STOCK MARKET RISE
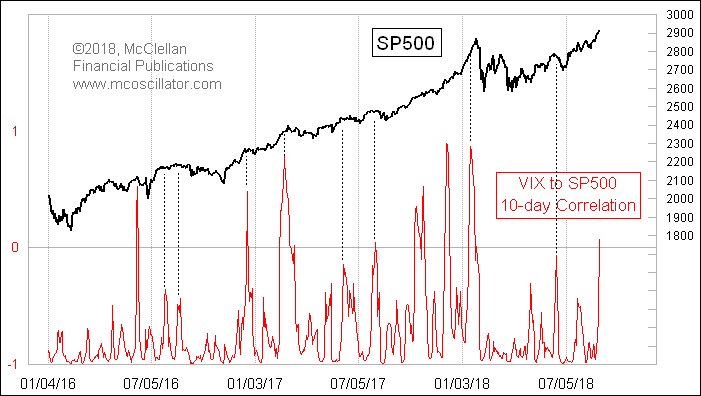
Something of interest, which might be nothing, is that the volatility index (VIX), often called the fear index, rose this week in tandem with stocks. Normally, there is a negative correlation. When stocks go up, the VIX normally goes down, and the opposite. But recently there has been a positive correlation. The last time that happened was right before the correction we had earlier this year. This correlation has sometimes occurred before previous sell-offs as well as shown below.
YIELD CURVE
New research based on the yield curve from the San Francisco Fed shows that the risk of a recession is rising but a downturn is far from certain. As the difference between short and long-term Treasury’s narrows, there is growing likelihood that the curve will invert, meaning that short-term rates will yield more than long-term rates. While the two and ten-year Treasury’s are most commonly discussed when determining yield curves, the San Francisco Fed says that the difference between the 10-year and the three-month bill is the more useful indicator. While the 2-10 spread is tight at 24 basis points, the difference between the three-month and ten-year is much wider, at 75 basis points.
SCOREBOARD
HIGHLIGHTS
MARKET RECAP
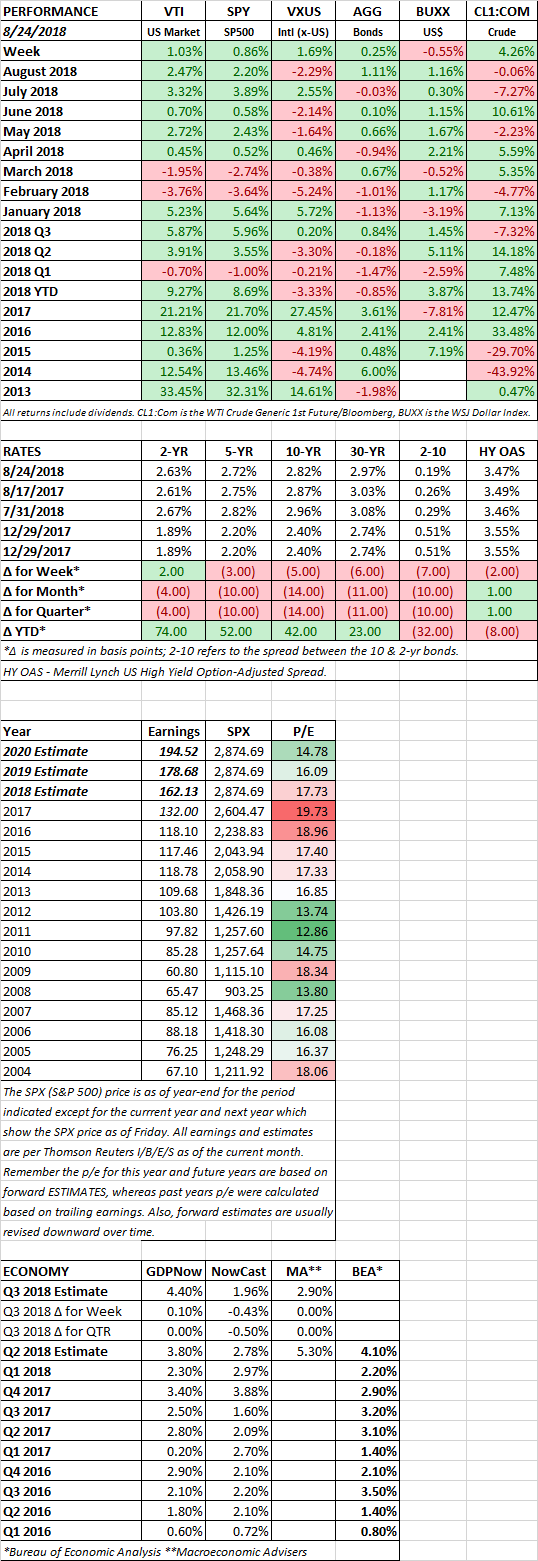
The S&P 500 closed at an all-time high, finishing at 2,874.60 on Friday. That beat out the previous high on January 26 of 2,872.87. Overall, US markets were up 1.03% and international stocks jumped 1.69%.
BAD POLITICAL NEWS
Markets advanced despite a swirl of bad political news, even by the standards of the Trump administration. Trump’s so-called “fixer” and former lawyer pled guilty to bank and tax fraud, campaign finance violations and said that Trump had directed him to pay money to two women to keep quiet on past relationships. Then former campaign chairman Paul Manafort was convicted on 8 different charges. It was reported that David Pecker, CEO of American Media (National Enquirer) and Allen Weisselberg, CFO of the Trump Organization, had received immunity from prosecution.
Pepsi said it would buy SodaStream International for $3.2 billion.
US / MEXICO
It is reported that the U.S. and Mexico are close to finalizing a NAFTA deal as soon as Monday. Breakthroughs in automobiles and energy and helping accelerate the talks. Canada would next need to get on board after the US and Mexico reach an agreement.
SCOREBOARD