Week Ending 11/6/2026

MARKET RECAP

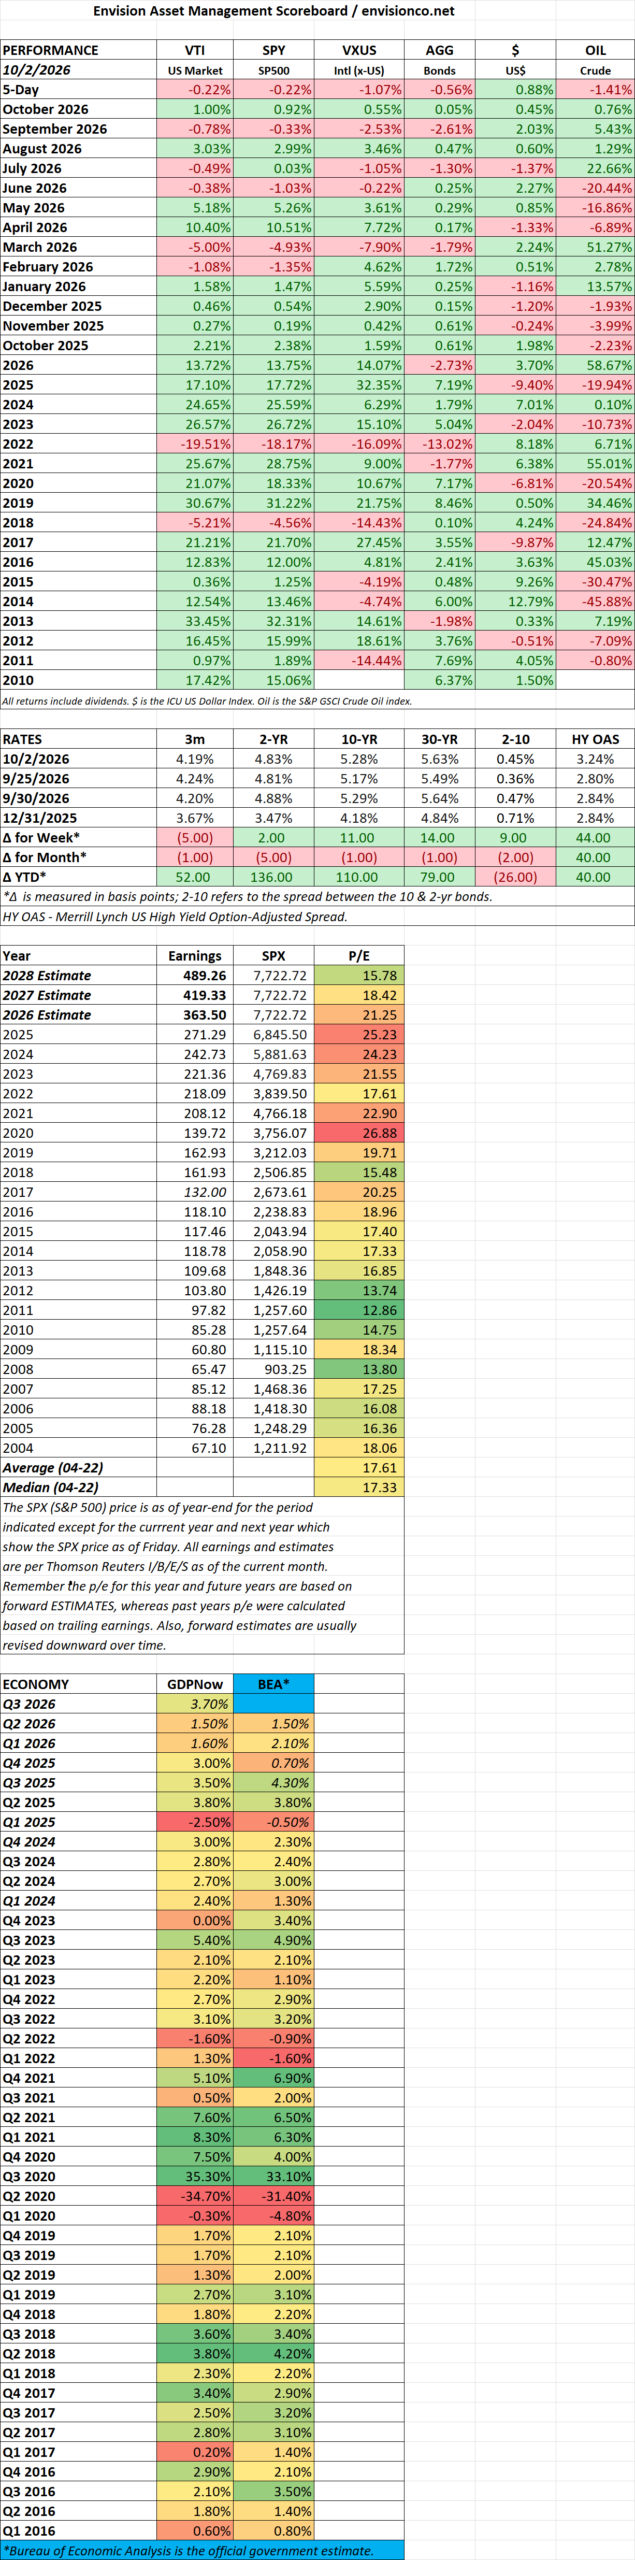
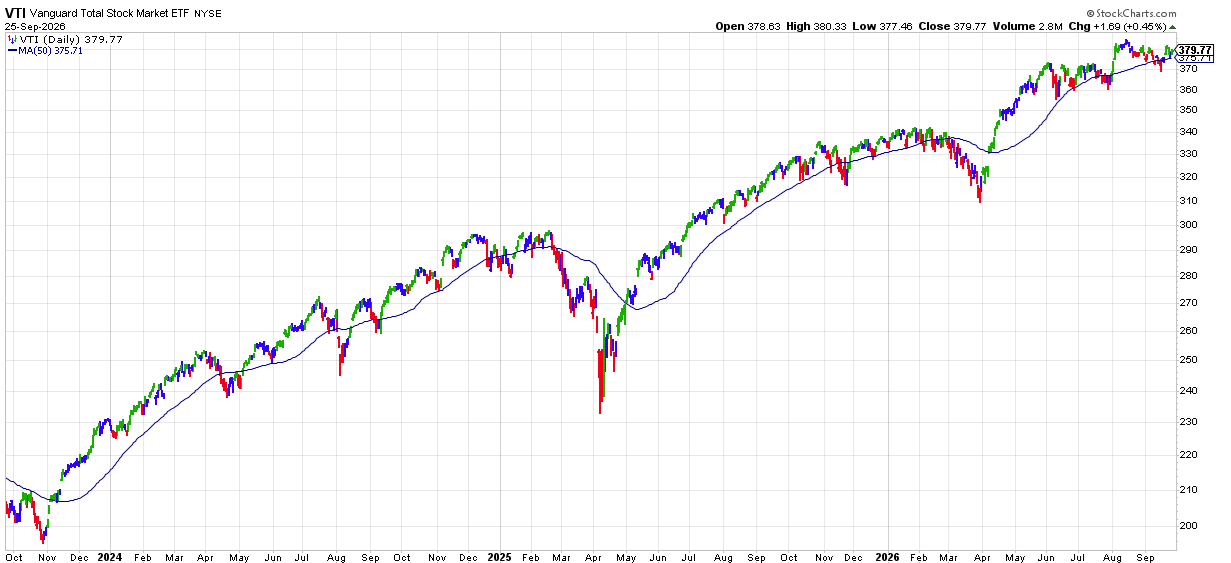
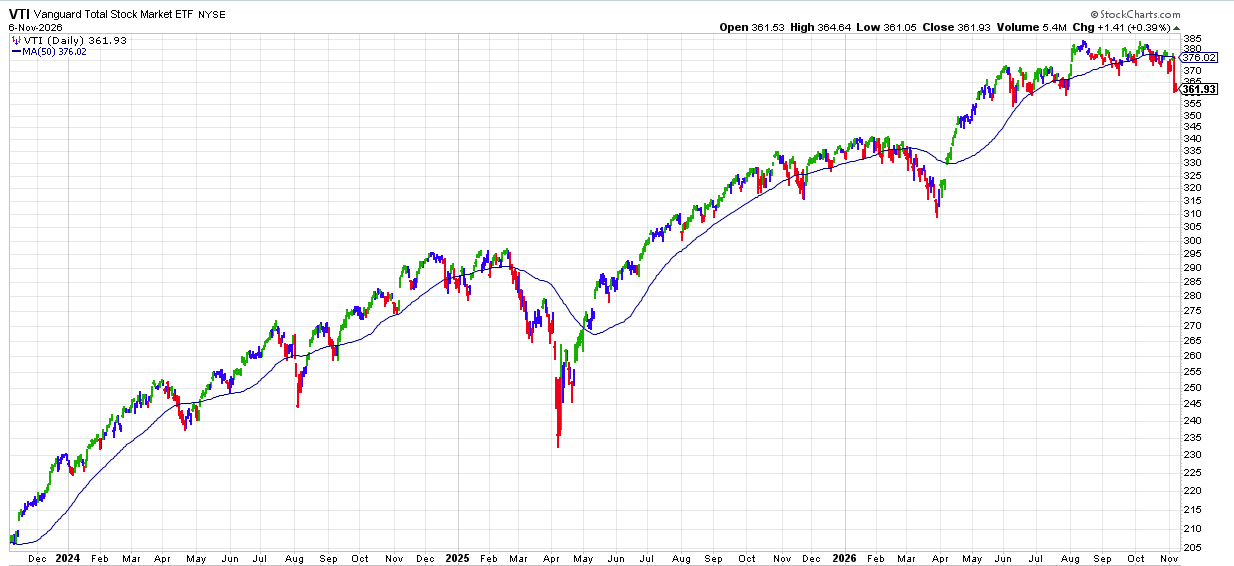
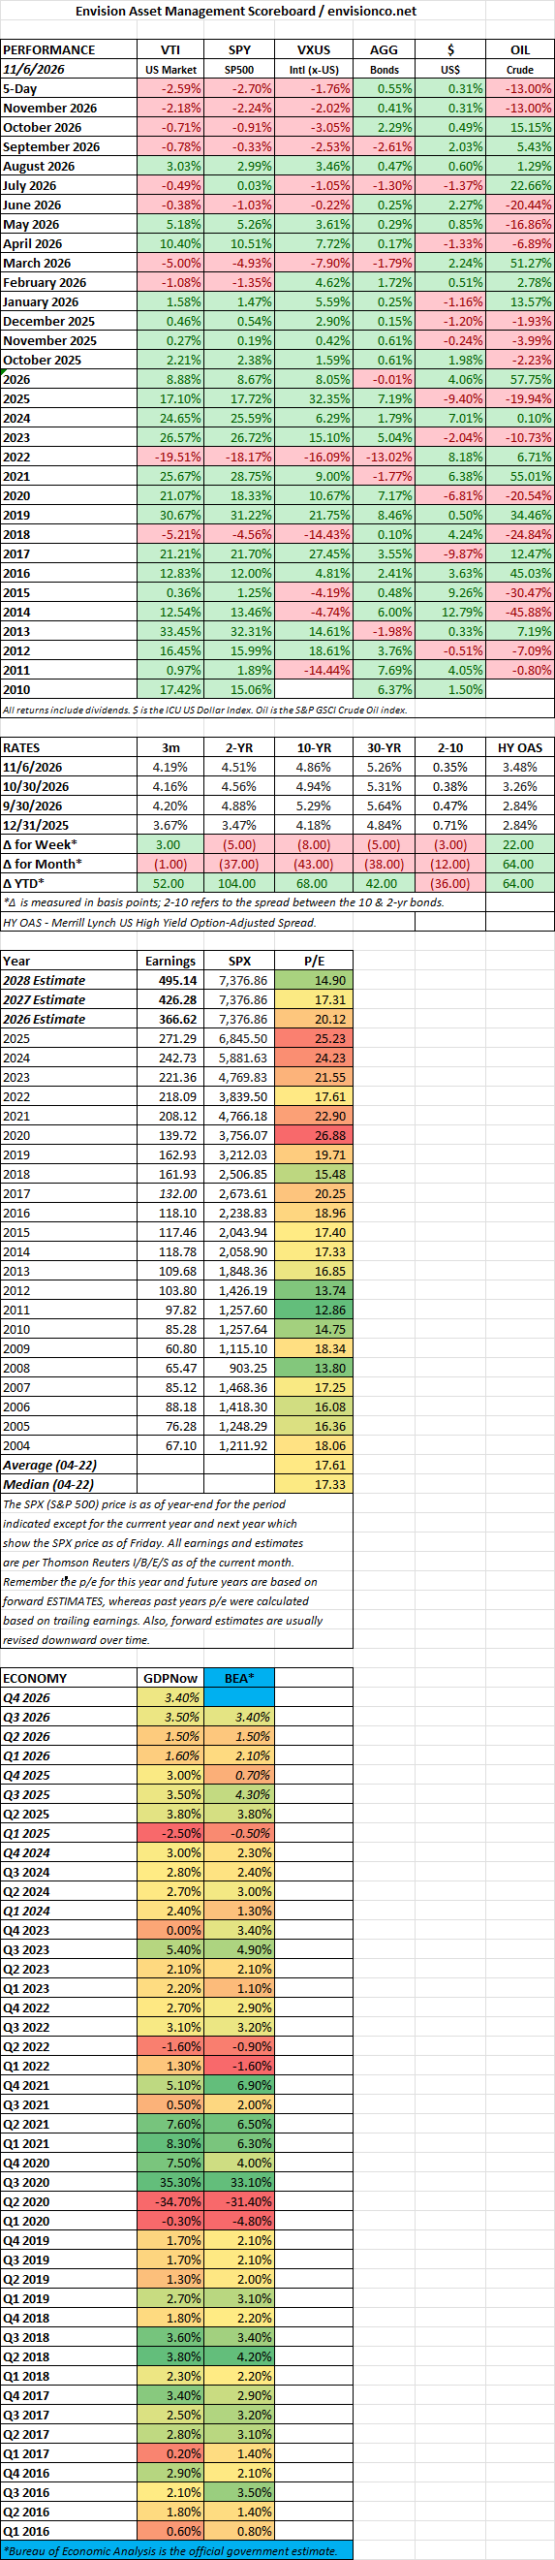
U.S. stocks ended a volatile election week lower, with Thursday’s technology rout overwhelming Wednesday’s rally. For the week ended November 6, 2026, the S&P 500 fell 2.68% to 7,376.86, the Dow Jones Industrial Average declined 0.94% to 51,285.73, and the Nasdaq Composite lost 3.37% to 24,579.42. The S&P 500 and Nasdaq recorded their fourth consecutive weekly declines. Small-cap shares also weakened, with the Russell 2000 down approximately 2.05%.

The midterm elections produced Democratic victories in both chambers of Congress, setting up divided government when the new Congress takes office in January. Wednesday’s initial market response was positive: the S&P 500 gained 1.58%, and the Dow rose 3.03%, as investors assessed the political outcome and sharply lower oil prices. However, data-center stocks were already falling as investors considered whether newly elected officials could slow infrastructure expansion.

Thursday brought a much broader selloff. The S&P 500 dropped 4.36%, the Nasdaq fell 5.52%, and the Dow lost 3.44%. Semiconductor shares plunged more than 12%, and the Nasdaq closed in correction territory—more than 10% below its recent peak. Concerns about possible restrictions on data-center construction compounded existing doubts about AI investment costs and returns. These were fears about future policy, rather than evidence that new restrictions had already taken effect.

The concerns extended beyond Washington. Investors focused on state and local permitting, electricity demand, and water use, all of which could affect the pace of construction. Companies dependent on borrowing to finance expansion faced additional scrutiny. Friday brought a partial recovery: the S&P 500 gained 0.31%, the Nasdaq rose approximately 1.1%, and semiconductor shares rebounded 4.2%, while the Dow slipped another 0.46%.

International stocks and bonds held up better than U.S. technology shares. The Vanguard Total International Stock ETF (VXUS) closed at $80.92, approximately 1.76% below the previous Friday. The 10-year Treasury yield finished near 4.86%, down 7 basis points for the week, although it rose Friday following the stronger employment report.

Gold recovered while Bitcoin declined. Spot gold finished near $4,066 an ounce, approximately 4.9% above the prior Friday’s reported level. Bitcoin’s Yahoo Finance daily closing price fell 1.88% to approximately $75,747. Cryptocurrency prices remained sensitive to regulatory concerns and the aftermath of the previous week’s Binance theft. These figures measure Friday-to-Friday performance; cryptocurrency trading continues through the weekend.

The economic reports showed stronger hiring and continued manufacturing expansion. October payrolls increased 165,000, substantially above forecasts near 65,000, while unemployment edged down to 4.1%. August and September payroll gains were revised upward by a combined 84,000, including a revision of September’s increase from 29,000 to 60,000. Average hourly earnings rose 0.4% monthly and 3.1% annually.

Initial unemployment claims fell to 189,000 for the week ended October 31. ISM’s manufacturing index increased to 55.5 from 54.5, indicating faster expansion, while September job openings stood at approximately 7.5 million. The stronger labor figures kept the possibility of a December Federal Reserve rate increase in focus despite the week’s decline in Treasury yields.

Oil’s decline was another major development. U.S. crude ended near $90.83 a barrel and Brent near $98.32, sharply below the preceding week’s levels. Hopes that the election outcome could encourage de-escalation with Iran contributed to the move. Lower energy prices offered potential relief for consumers and businesses, while weighing heavily on energy shares. Markets now turn to the coming week’s inflation reports for further evidence about the interest-rate outlook.

US STOCK MARKET (VTI)
SCOREBOARD
Too Much, and Wrong – the landslide knocks out the Republicans

The Republicans got pummeled on Tuesday. Democrats took the House and the Senate. Nobody should be surprised. This was a predictable backlash against the craziness of the Trump era.

It’s worth remembering how we got here. In the last two presidential elections, both Biden and Trump treated their wins as mandates. They weren’t. Both elections were close, and each man drew many votes from people simply protesting the president he replaced. That isn’t a mandate. It’s a warning.

Biden ignored the warning. He went overboard with woke policies, and he let immigration and the border get out of control. The response was Trump’s victory.

Then Trump made the same mistake, only bigger.

Start with the economy. Trump’s tariff policies had no economic basis. They caused major dislocations and lost efficiency across the economy. And here is the irony: Trump was elected in part because of the high inflation of the Biden years, and then his signature economic policy was tariffs, which led to more inflation. He went after Canada non-stop, killing Republican chances in Michigan and Maine and leading to more inflation. He just makes some terrible decisions.

On immigration, Trump was right. He got the border under control, and he did a great job closing it. He was right to remove criminals who were here illegally. But then he went way overboard, going after illegal immigrants who were otherwise law-abiding. That was too much.

On the rule of law, he was simply wrong. For years, Trump complained that he was being prosecuted for political reasons. Then he turned around and did the same thing to his opponents. Too much, and wrong. He pardoned or freed every one of the January 6th criminals. A terrible signal, and wrong.

On Iran, Trump was right about the objective. Iran cannot be allowed to get a nuclear weapon. But he never clearly explained his strategy or why it mattered, and the facts would have been on his side. The war is now in its ninth month, and the execution has not been good. Hopefully it can still be resolved and the objective reached positively.

Meanwhile, he spent far too much time on nonsense. He tore down the East Wing to build a $400 million ballroom. He spent $16 million on a rushed, no-bid redo of the Lincoln Memorial Reflecting Pool that soon peeled and became full of algae. And there was a lot of questionable behavior, behavior that would appear to be unethical, around the business and crypto ventures his family got involved in. Those ventures made them billions.

Trump also gave away races Republicans should have won. Again and again he backed candidates whose main qualification was 100% loyalty to him over really good incumbents. In Texas, he backed Ken Paxton over John Cornyn. Paxton won the primary and then lost to a Democrat, the first Democratic Senate win in Texas since 1988. In North Carolina, Thom Tillis retired after Trump threatened to back a primary challenger, and Trump’s hand-picked replacement lost the seat. In Louisiana, Trump pushed out Bill Cassidy, and that seat was saved only because Louisiana is so deeply red. When Lindsey Graham passed, Trump threw his support behind Lindsey’s sister, Darline Graham, for the South Carolina seat. She had never held elected office, and her main qualification was being Lindsey’s sister. She lost.

How Trump was elected, I will never understand. And I mean both times. The warning signs were everywhere from the very beginning. The Republicans would have been much better served by a traditional Republican: Nikki Haley, Marco Rubio, Mitt Romney, Ted Cruz, or many others.

The bigger problem goes beyond one party. Both parties keep ignoring the deficit. We have been writing about this for years. Both parties continue to ignore the problems with Social Security. The fixes are no mystery:

  • The problem is clearly on the spending side, but we need a slight tax increase along with a freeze or cut in spending.
  • Raise the Social Security retirement age.
  • Cut benefits for the well-off.
  • Raise the limit on income subject to Social Security taxes.
  • Aggressively root out fraud in government. AI tools should make this much easier.
  • Restaff the IRS so everyone pays the proper amount of tax under the law.

None of this is radical. A well-run business would do all of it. But we don’t have adults running Washington. We have irresponsible leaders.

Hopefully the rout of the Republicans puts an end to the Trump wing of the party, and the party can get back to its traditional values. Of course, the maniacs on the Democratic side are even worse. The country needs to be governed from the middle. By some miracle, maybe that can happen in the next few years.

Week Ending 10/30/2026

MARKET RECAP

U.S. stocks surrendered their early-week gains as technology shares came under renewed pressure. For the week ended October 30, 2026, the S&P 500 declined 0.57% to 7,580.07, the Dow Jones Industrial Average lost 0.85% to 51,770.31, and the Nasdaq Composite fell 2.00% to 25,437.00. Smaller companies performed better: the Russell 2000 gained approximately 1.3%, despite joining Friday’s selloff.

Earnings reports intensified scrutiny of technology companies’ spending and cash generation. Alphabet’s results prompted a sharp Thursday decline, while Amazon’s investment plans and Intel’s outlook added pressure late in the week. Intel fell approximately 28.6% Friday, helping drive a 7.2% daily decline in semiconductor shares. Energy companies provided a counterweight, with Exxon Mobil and Chevron benefiting from stronger-than-expected profits.

International stocks posted a modest weekly decline, while Treasury prices rose. The Vanguard Total International Stock ETF (VXUS) closed at $82.37, down approximately 0.19% from the previous Friday. The 10-year Treasury yield ended near 4.93%, about 6 basis points lower for the week. Spot gold was quoted near $3,876 late Friday, roughly 3% below the prior Friday’s level.

Bitcoin declined as a major exchange theft shook confidence in cryptocurrency markets. Its reported daily closing price fell approximately 4.8% for the week to $77,198. Hackers stole approximately $6.3 billion in digital assets from Binance on October 29, including bitcoin and other tokens. Binance suspended withdrawals and said it would cover customer losses using its protection fund and corporate resources.

The Federal Reserve paused, but inflation remained a concern. On October 28, policymakers voted 10–2 to maintain the federal funds target range at 3.75%–4.00%. Governor Lisa Cook and Cleveland Fed President Beth Hammack preferred a quarter-point increase. The statement described strong economic growth and elevated inflation, leaving subsequent decisions dependent on additional information.

New economic reports showed stronger quarterly growth alongside continued price pressures. The advance estimate put third-quarter real GDP growth at a 3.4% annualized rate, up from 2.2% in the second quarter. September’s PCE price index increased 0.5% for the month and 3.6% over the year; excluding food and energy, inflation measured 0.3% monthly and 3.1% annually. Consumer spending rose 0.5% in dollar terms but was essentially unchanged after inflation.

Layoffs remained low, while compensation costs continued rising. Initial unemployment claims declined 1,000 to 194,000 for the week ended October 24, and continuing claims fell 21,000 to 1.701 million for the preceding week. Separately, the Employment Cost Index showed total compensation rising 0.8% during the third quarter and 3.4% over the year.

Elevated oil prices and the possibility of renewed U.S. strikes on Iran added geopolitical uncertainty. U.S. crude finished Friday at $104.12 a barrel, with Brent near $117.63 amid continuing Middle East supply risks. Asked October 28 about additional strikes after the midterms, President Trump said “anything’s possible,” leaving military action open without announcing a decision. The prospect of escalation remains relevant to energy supplies, inflation, and business costs.

This week’s midterm elections will help determine the policy backdrop for the next two years. Ahead of the November 3 vote, polls and analysts favored Democrats to capture the House, while control of the Senate remained too close to call. A Democratic House could impede legislation and increase oversight of the administration, although Trump would retain veto power and substantial executive authority. Investors will assess the implications for taxes, spending, trade, and regulation alongside Friday’s October employment report.

US STOCK MARKET (VTI)

SCOREBOARD
Trump Accounts Just Changed: Automatic Enrollment and Individual Stocks

Trump Accounts Just Changed: Automatic Enrollment and Individual Stocks

If you have a child under 18 with a Social Security number, that child now has a Trump Account, whether or not you opened one. New rules from Treasury and the IRS, issued September 30, 2026, made two big changes: accounts are now opened automatically for eligible children, and charitable donors can now contribute shares of individual companies.

As a quick refresher, Trump Accounts (formally Section 530A accounts) are a type of IRA for minors created by the One Big Beautiful Bill Act. Families could start signing up when the Trump Accounts app launched on July 4, 2026. U.S.-citizen children born from January 1, 2025, through December 31, 2028, are eligible for a one-time $1,000 federal seed contribution. Philanthropists have pledged more. The largest is Michael and Susan Dell’s $6.25 billion pledge, which provides $250 to children age 10 and under who live in ZIP codes with median household income below $150,000.

Even so, sign-ups were slow. Before the new rules, Treasury had processed about 5.6 million sign-up forms, out of roughly 73 million eligible children.

Change 1: Every eligible child now has an account

On or about October 1, 2026, the IRS opened an “auto account” for every eligible child with a Social Security number who didn’t already have one. It will keep adding accounts as more children become eligible. Treasury estimated this would add more than 60 million accounts, and the White House now puts the total at nearly 70 million.

There is currently no way to opt out. Treasury has asked for public comment on a limited “disclaimer” option. As described, it would apply only to unclaimed accounts that never received the $1,000 seed, and only once the child is at least 18.

The main benefit is access to charitable money. Charities and governments make “general contributions” to groups of at least 5,000 children defined by age or geography, and only children with an account can receive them. An account doesn’t guarantee a gift. That depends on whether your child falls into a group a donor chooses.

Until it is claimed, an auto account is limited:

  • It can receive charitable and government contributions, but not money from parents, grandparents, or employers.
  • Treasury acts as the responsible party, and the assets are held collectively in a master trust.
  • If it never receives any money, it is closed after the child’s “growth period” ends (December 31 of the year the child turns 17).

Why you should claim your child’s account

To take control, a parent or guardian must claim the account through the official Trump Accounts app or TrumpAccounts.gov and verify their identity. Claiming moves the balance into a regular Trump Account that you manage.

We recommend claiming each child’s account, even if you don’t plan to add money:

  • To receive the $1,000 seed. Children born 2025 through 2028 need a claimed account to get the federal contribution.
  • To add money. Family and employer contributions, up to $5,000 per year, can only go into a claimed account.
  • To protect your child’s identity. An unclaimed account in your child’s name is one more thing someone using stolen information could try to take over.
  • To keep track of gifts. If a donor deposits cash or stock, you’ll want to see it and manage it.

Change 2: Donors can now give individual stocks

Trump Accounts are generally limited to low-cost U.S. stock index funds. The new rules let charities and governments make their group contributions in publicly traded stock of U.S. companies instead of cash. Treasury’s reasoning is that holding a donated stock doesn’t break the investment limit, because no money in the account was used to buy it.

The stock comes with strings attached. It generally can’t be sold until the earlier of five years after the gift or the end of the child’s growth period, with narrow exceptions such as a tender offer. Once it can be sold, the proceeds must be reinvested in an eligible index fund within 30 days.

The goal is to attract larger gifts. Many major donors hold most of their wealth in company stock, and Treasury expects these gifts to bring in billions of dollars a year.

The tradeoff falls on families. If your child is in a group a donor chooses, you don’t pick the stock and can’t sell it during the holding period. A single company can rise or fall far more than a diversified fund. Your own contributions, employer contributions, and the $1,000 seed still go into eligible index investments, so the more the account holds from those sources, the less any one stock matters.

What this means for your family

You may no longer get to decide whether your child has a Trump Account, or what a donor puts in it. You can still decide how the account is protected and managed from here.

  1. Claim the account for each child under 18 through the Trump Accounts app or TrumpAccounts.gov, even if you don’t plan to fund it.
  2. Watch for deposits from the federal seed program or charitable donors.
  3. Know what it holds. If a single-stock gift arrives, factor that concentration into your family’s overall plan.
  4. Decide on your own contributions in the context of other goals, such as 529 plans, custodial accounts, or your own retirement savings.

These are temporary regulations, and Treasury is taking public comments through late November 2026, so details may change. If you have children or grandchildren under 18 and want help sorting through these changes, please reach out to us.

Sources

Week Ending 10/23/2026

MARKET RECAP

U.S. stocks ended the week of October 23, 2026, with gains outside the largest technology companies helping offset continued weakness in growth shares. The S&P 500 declined 0.47% to 7,623.68, and the Nasdaq Composite lost 0.71% to 25,955.34. The Dow Jones Industrial Average gained 0.41% to 52,215.16, while the small-company Russell 2000 advanced approximately 2%. That divergence showed that selling pressure was uneven across the market.

Corporate earnings brought the costs and potential returns of artificial intelligence investment into sharper focus. Meta’s increased spending outlook unsettled investors, while Tesla’s reduced capital-spending forecast raised different questions about its growth plans. Both companies’ shares fell following their reports, illustrating investors’ sensitivity to how businesses balance investment, profitability, and cash flow.

International stocks declined, while Treasury prices strengthened. The Vanguard Total International Stock ETF (VXUS) closed at $82.53, down 1.08% from the previous Friday. The 10-year Treasury yield ended near 4.99%, approximately 11 basis points below the prior week’s close, although yields rose on Friday. Bitcoin remained near $81,000 late in the week, slightly below the previous Friday’s level; prices vary by exchange and measurement time.

Energy prices were an important source of inflation concern. Brent crude finished Friday at $116.72 a barrel, and U.S. benchmark West Texas Intermediate settled at $103.27, as attacks in Saudi Arabia heightened fears of supply disruptions. Gold moved lower despite geopolitical uncertainty: spot prices traded around $4,000 an ounce Friday and were down approximately 4% for the week at the time of reporting. December gold futures settled at $4,007.90.

Labor data continued to show limited layoffs alongside slow hiring. Initial unemployment claims fell 6,000 to 194,000 for the week ended October 17, from an upwardly revised 200,000. Continuing claims, which cover the preceding week, rose 25,000 to 1.728 million. For context, September’s employment report—released October 2—showed payroll growth of only 29,000, an unemployment rate of 4.2%, and annual average hourly earnings growth of 3.0%. Low claims therefore did not necessarily signal strong demand for additional workers.

Friday’s preliminary business survey offered another important economic signal. S&P Global’s U.S. Composite PMI eased to 57.6 in October from 58.4 in September but remained comfortably above the 50 threshold separating expansion from contraction. Businesses also reported stronger selling-price pressures, suggesting that continued economic growth was accompanied by persistent inflation risks.

Attention now turns to the Federal Reserve’s October 27–28 meeting, with markets expecting unchanged interest rates. The following day brings the advance estimate of third-quarter GDP and September’s Personal Consumption Expenditures inflation report. Earnings from Microsoft, Alphabet, and Amazon will also provide further evidence about technology spending and corporate profitability.

SCOREBOARD

Week Ending 10/16/2026

MARKET RECAP

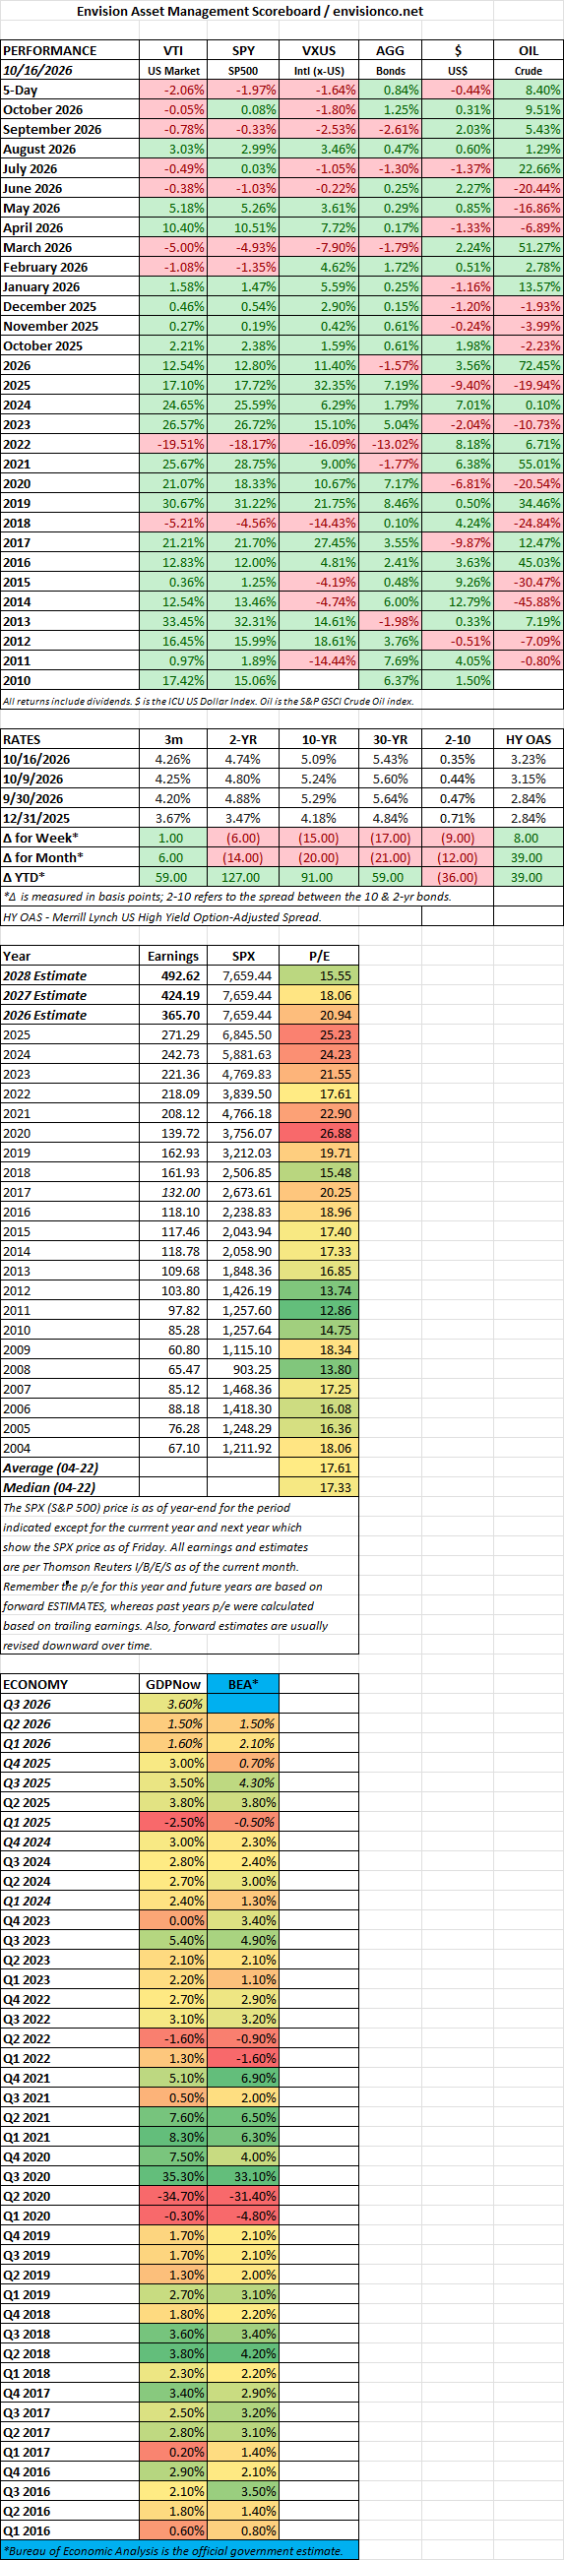
U.S. stocks took different paths during the week ended October 16, 2026. The S&P 500 declined 1.95% to 7,659.44, and the Nasdaq Composite lost 4.48% to 26,140.03. The Dow Jones Industrial Average gained 0.67%, finishing at 52,002.41. Technology shares were a major source of weakness, with semiconductor companies under pressure as investors questioned the durability of spending on artificial intelligence infrastructure.

International stocks also declined. The Vanguard Total International Stock ETF (VXUS), a broad measure of developed and emerging markets outside the United States, closed at $83.43, down 1.64% from the previous Friday. Meanwhile, the benchmark 10-year Treasury yield fell approximately 15 basis points to 5.10%. Lower Treasury yields provided support for bond prices despite the week’s stronger inflation readings.

Bitcoin’s October 16 daily closing price on Yahoo Finance was approximately $81,501, about 1.27% below its October 9 close. Spot gold traded near $4,165 an ounce Friday afternoon and was down approximately 0.7% for the week at that point. December gold futures settled at $4,181.10.

Inflation remained a central concern. September’s Consumer Price Index increased 0.6% for the month and 3.7% over the preceding year. Excluding food and energy, prices rose 0.3% monthly and 2.6% annually. Gasoline accounted for more than half of the headline monthly increase.

Producer prices rose 1.3% in September, while retail sales increased 0.8%, partly reflecting higher gasoline costs. Initial unemployment claims increased slightly to 199,000. September’s monthly employment report had already been released on October 2 and was outside this week’s reporting calendar.

The divergence between the Dow and Nasdaq highlighted the uneven nature of the selling. Concerns about AI investment and financing weighed on technology companies, while persistent price pressures complicated expectations for Federal Reserve policy. Upcoming earnings reports and policymakers’ comments will offer investors more information about corporate prospects and the outlook for interest rates.

SCOREBOARD

Week Ending 10/9/2026

MARKET RECAP

U.S. equities advanced for the week ended October 9, 2026, setting fresh records as defensive sectors and energy led the market higher.

Major benchmarks posted solid gains from the prior Friday close:

  • S&P 500: Rose 1.15% to 7,811.54, after setting an all-time high midweek.

  • Dow Jones Industrial Average: Gained 0.93% to finish at 51,654.95.

  • Nasdaq Composite: Advanced 0.64% to close at 27,366.17.

Sector leadership rotated toward utilities, consumer staples, and energy. Conversely, semiconductor shares faced midweek headwinds after reports indicated OpenAI’s revenue growth was tracking below earlier aggressive targets. Crude oil prices remained volatile throughout the week amid lingering geopolitical friction involving Iran.

Performance across international equities, fixed income, and commodities:

  • International Equities: The Vanguard Total International Stock ETF (VXUS) declined 0.71%, falling from $85.43 to $84.82.

  • Fixed Income: The 10-year Treasury yield edged lower, settling near 5.24%—down 4 basis points from the prior Friday’s 5.28% and below an intra-week high near 5.31%—as fixed-income markets continued to absorb the prior week’s subdued jobs data.

  • Commodities: Gold rose 1.3% to settle near $4,195 per ounce, recovering from the prior week’s close of $4,141.

  • Cryptocurrency: Bitcoin retreated approximately 2.3%, closing near $82,560 compared to $84,500 the prior Friday.

The week’s economic calendar was anchored by labor stability, monetary policy signals, and consumer confidence:

  • Labor Market: Initial jobless claims for the week ended October 3 came in at 197,000. This marked the fourth consecutive week below 200,000, underscoring a persistent “low-hire, low-fire” environment with minimal layoff activity.

  • Federal Reserve: The release of the September FOMC meeting minutes confirmed that a majority of policymakers still favor one additional interest rate hike before year-end to ensure inflation returns to target.

  • Sentiment: The preliminary University of Michigan consumer sentiment survey showed readings remain subdued amid higher borrowing costs. No major monthly inflation data was released during the week.

Large-cap domestic equities demonstrated durability in the face of elevated benchmark yields, choppy energy markets, and a hawkish Fed posture. Market attention shifts directly to next Wednesday’s September CPI report and the unofficial kickoff of third-quarter earnings season led by major financial institutions.

SCOREBOARD

Week Ending 10/2/2026

MARKET RECAP

U.S. stocks finished mixed for the week ended October 2, as a cooling September employment report sparked a Friday relief rally that partially offset earlier losses.

Major averages diverged as mega-cap technology buoyed the broader market:

  • S&P 500: Slipped 0.27% to close at 7,722.72.

  • Dow Jones Industrial Average: Dropped 1.26% to finish at 51,176.96.

  • Nasdaq Composite: Gained 0.45% to settle at 27,190.86 after briefly touching an intraday record high.

Friday’s rebound—which saw gains of roughly 0.7% for the S&P 500, 0.5% for the Dow, and 1.2% for the Nasdaq—came as traders pared back expectations for another near-term Federal Reserve rate hike.

Across global markets and other asset classes:

  • International Equities: Vanguard Total International Stock ETF (VXUS) lagged domestic equities, falling roughly 1.1% to close at $85.43.

  • Fixed Income: Despite easing into the weekend following the jobs release, the 10-year Treasury yield rose 11 basis points over the week, moving from 5.17% to 5.28% due to early-week crude strength and lingering inflation concerns.

  • Commodities: Gold slid 3.4% to finish near $4,141 per ounce—marking one of its sharpest weekly declines in months—pressured by elevated real yields and a firmer U.S. dollar.

  • Cryptocurrency: Bitcoin traded relatively flat, finishing near $84,500 compared to approximately $84,000 the prior Friday.

The week’s primary catalyst was Friday’s September jobs report, which pointed to significant labor-market deceleration:

  • Nonfarm payrolls increased by just 29,000, falling well short of the 90,000 consensus estimate.

  • The unemployment rate edged higher to 4.2% from 4.1%, while prior months’ payroll additions were revised downward.

  • Annual wage growth slowed to 3.0%, registering its softest pace since May 2021.

Secondary economic data presented a more balanced picture. Initial jobless claims for the week ended September 26 dipped to 197,000, matching July lows, while continuing claims fell to approximately 1.70 million. Additionally, August core PCE inflation came in cooler than expected at 3.0% year over year, reinforcing the view that the Fed has room to pause and assess incoming data.

Geopolitical developments and single-stock headlines dictated intraday price swings. Crude oil fluctuated after President Trump rejected an Iranian proposal on navigation in the Strait of Hormuz, then eased as Gulf energy flows showed signs of recovery and mediation efforts continued. On the corporate front, Nike’s cautious remarks on Chinese consumer demand weighed on retail sentiment, while strength across large-cap semiconductors, including Nvidia, propelled tech outperformance.

While signs of a cooling labor market gave equities late-week footing, elevated bond yields and persistent geopolitical tension around Persian Gulf shipping leave markets attentive ahead of upcoming inflation reports.

SCOREBOARD

Week Ending 9/25/2026

MARKET RECAP

U.S. stocks finished higher for the week ended September 25, rebounding through a choppy stretch marked by crude oil volatility, climbing Treasury yields, and hopes that energy disruptions around the Strait of Hormuz might ease.

Large-cap technology and AI-related names led the rebound, helping the major averages overcome a midweek dip to close Friday with solid weekly gains:

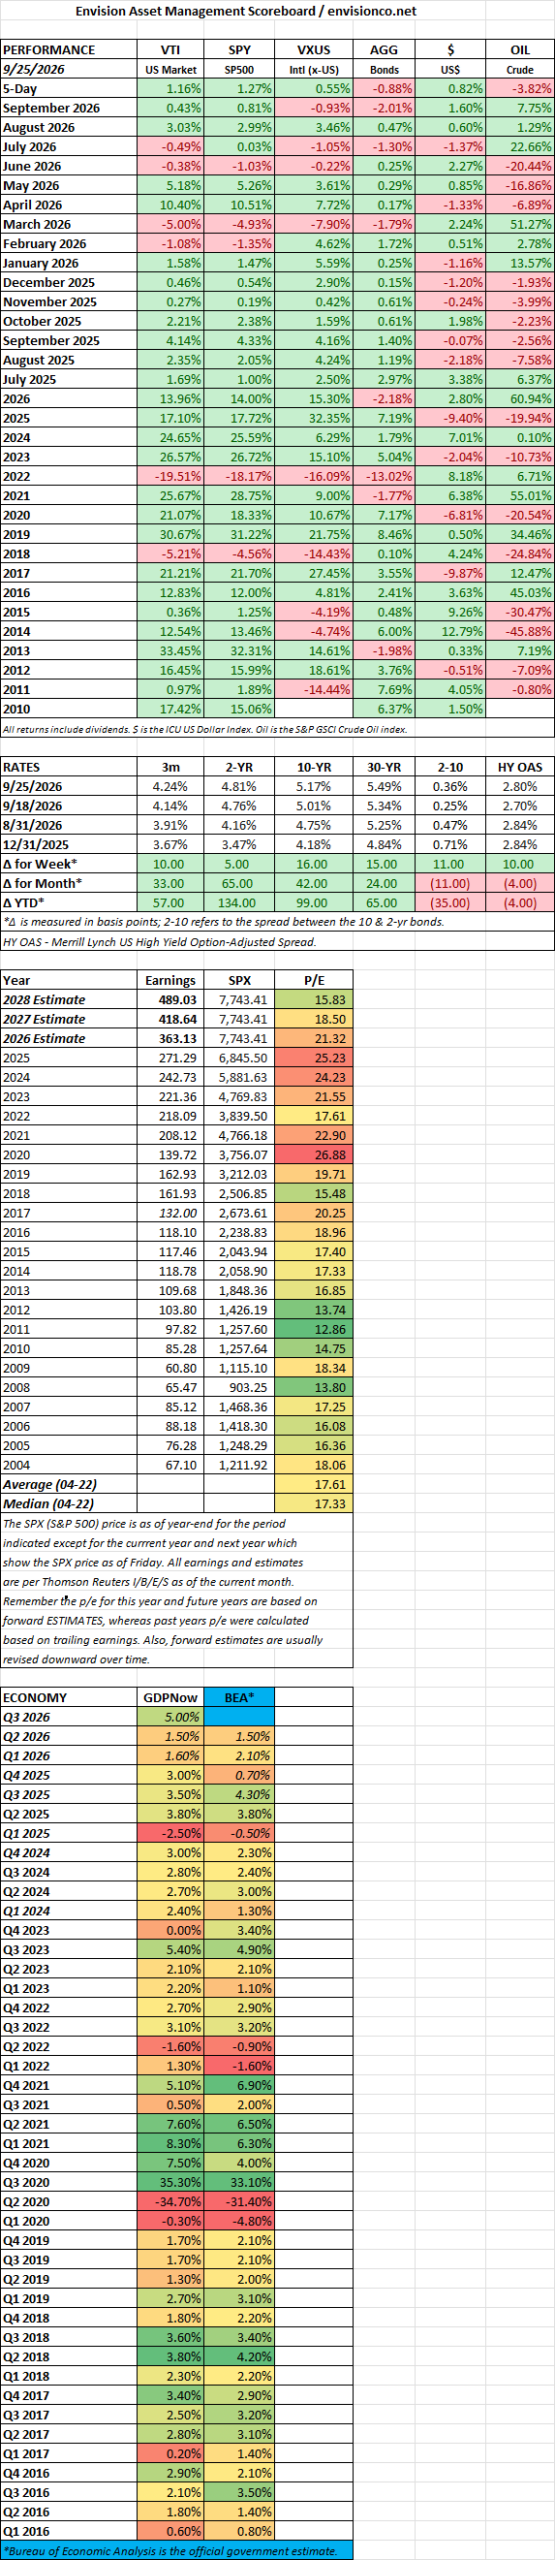
  • S&P 500: Rose 1.21% from the prior Friday to close at 7,743.41.

  • Dow Jones Industrial Average: Added 0.28% to finish at 51,828.62.

  • Nasdaq Composite: Outperformed with a 2.06% gain, settling at 27,068.72.

Market Breadth: Cap-Weighted vs. Equal-Weighted

The tech-led rally highlighted a recurring divergence in market breadth. Over the past month, the cap-weighted S&P 500 resumed its outperformance over the equal-weighted index (Invesco S&P 500 Equal Weight ETF, RSP). While RSP outpaced the broader market during late summer as participation broadened, September’s advance narrowed back toward mega-cap technology and AI leaders, causing the equal-weighted benchmark to lag the headline index over the rolling four-week stretch.

International Equities, Fixed Income, and Commodities

  • International Equities: Vanguard Total International Stock ETF (VXUS) saw a more muted recovery, ticking up 0.55% to close at $86.35.

  • Fixed Income: The 10-year Treasury yield rose roughly 18 basis points to finish near 5.17%–5.18%—its highest area since 2007—as hawkish Fed commentary and firm activity kept another rate hike on the table.

  • Cryptocurrency: Bitcoin gained approximately 4.0%, advancing from around $80,900 on September 18 to $84,100.

  • Commodities: Gold retreated under pressure from higher real yields and a firmer U.S. dollar, with COMEX futures down 2.3% to settle near $4,286 per ounce.

Economic Data & Corporate Earnings

The calendar brought no major monthly inflation or GDP releases this week, leaving markets to trade off secondary data and prior policy signals. Initial jobless claims dipped to 197,000 for the week ended September 19, signaling historically low layoff activity. Earlier releases—including August CPI (3.4% YoY), core PCE (3.3%), and the Q2 GDP estimate (1.5% annualized)—continued to underpin the Fed’s recent quarter-point rate hike to a 3.75%–4.00% target range and its hawkish guidance.

Corporate fundamentals, however, remain a strong pillar of support:

  • Q2 2026 Earnings: The finalized blended earnings growth rate for the S&P 500 surged well above original projections, ultimately exceeding 23% year-over-year (and topping 50% on unadjusted headline EPS driven by mega-cap revisions), marking the index’s seventh consecutive quarter of double-digit earnings expansion.

  • Q3 2026 Outlook: Analysts remain uncharacteristically optimistic heading into the reporting period. Consensus estimates project Q3 year-over-year earnings growth of approximately 27% to 29%, bolstered by upward revisions in Information Technology, Energy, and Financials.

Geopolitics, Energy & Tech Catalysts

  • Diesel Export Ban Rumors: Intraday energy volatility surged midweek following reports that the White House was reviewing a potential 90-day ban on U.S. diesel exports to tame pump prices. Industry groups, including the American Petroleum Institute (API), warned that restricting exports would force Gulf Coast refiners to curtail runs and exacerbate fuel shortages. Energy Secretary Chris Wright and White House officials walked back the report by Wednesday, clarifying that a blanket ban is not on the table and calming crude markets into Friday.

  • Meta Muse Launch: Technology sentiment was buoyed by Meta’s rollout of Muse, its autonomous, multi-modal personal AI agent capable of executing complex end-to-end tasks, web navigation, and scheduling across desktop and mobile ecosystems. The launch reinforced investor conviction in commercial AI monetization, lifting mega-cap tech.

  • Global Trade: High-level meetings between President Trump and China’s Xi Jinping during U.N. week yielded limited incremental dialogue without delivering a meaningful breakthrough on structural trade disagreements.

Equities demonstrated resilience by absorbing another leg up in yields and elevated energy costs. Looking ahead, that underlying strength will be tested with the upcoming release of August PCE inflation figures, the final revision to Q2 GDP, and the September employment report.

US STOCK MARKET (VTI)

SCOREBOARD
Week Ending 9/18/2026

MARKET RECAP

U.S. stocks finished a choppy week mixed after the Federal Reserve delivered its first rate increase in three years and signaled that another hike remains on the table before year-end.

Performance diverged sharply across benchmarks:

  • S&P 500: Slipped 0.08% to close at 7,650.50.

  • Dow Jones Industrial Average: Dropped 1.69% to 51,682.64, logging its third consecutive weekly decline.

  • Nasdaq Composite: Rose 0.72% to 26,522.55, as resilience in semiconductors and mega-cap technology helped counterbalance broad weakness in financials and industrials.

Across other major asset classes:

  • International Equities: Vanguard Total International Stock ETF (VXUS) fell 1.45%, mirroring the pressure on non-U.S. risk assets.

  • Fixed Income: The 10-year Treasury yield rose from roughly 4.96% to finish near 5.00% on Friday, revisiting levels last seen in 2023 and keeping rate-sensitive sectors under pressure. The 2-year yield increased from 4.63% to 4.76%.

  • Cryptocurrency: Bitcoin rebounded into the weekend, finishing near $80,900 for a gain of roughly 4.8% from the prior Friday.

  • Commodities: Gold held steady, finishing virtually unchanged around $4,390 per ounce.

Labor data continued to support the central bank’s hawkish stance. Initial jobless claims fell to 196,000 for the week ended September 12—beating expectations and marking the lowest level since mid-July—while continuing claims also moved lower. Paired with the Fed’s quarter-point rate hike and firmer guidance, the figures kept market participants firmly focused on persistent inflation rather than the prospect of policy easing.

While markets absorbed the policy shift without a widespread sell-off, the pronounced divergence between technology and the broader tape—alongside a 10-year yield hovering at 5.00%—leaves sentiment guarded ahead of upcoming economic releases.

SCOREBOARD